How to Get Business Loan Approval in 24 Hours
Get business loan approval in 24 hours by choosing lenders that decide fast and preparing the documents they ask for first.
Nov 6, 2026Read
Messy books don't have to block your loan. Learn which records lenders check, how to clean up bookkeeping fast, and which financing paths may still work.
Quick Summary
Messy books do not automatically disqualify you from a business loan, but they make approval harder and slower. Lenders want proof your business is real, earns money, and can repay, so start by reconciling your bank and card accounts for the most recent three to six months.
Last Updated: November 7, 2026
Messy books do not automatically disqualify you from a business loan. But they make approval harder, slower, and less predictable.
Lenders look at your books because they cannot see your business directly. A clean set of records gives them a reliable picture of your revenue, your expenses, and your cash flow.
The federal government also points borrowers toward careful preparation. Small Business Administration explains that lenders typically ask for financial statements and other documents before deciding on a loan. U.S. Small Business Administration guidance on loan applications
Clean books do not have to be perfect. Lenders look for records that are complete, consistent, and current. Here is what they usually check:
If your books meet most of these points, you are in a much stronger position than you may think.
Some problems stand out quickly during underwriting. Watch for these red flags:
Watch out: Lenders often read unexplained deposits as possible revenue inflation. Always label a large deposit, even if it was a personal loan or an owner contribution.
Share of financing applicants by amount received
Received full amount sought 42%Received some or most of amount 36%Received none 22%Most lenders ask for a similar set of documents. Requirements vary by lender and loan type, so confirm the list before you apply. Gathering your paperwork early can shorten the process.
Lenders commonly ask for these items:
If your books are behind, you do not need every document to be perfect before you start. Ask the lender which items they need first. Some will accept bank statements and a simple revenue summary while you finish your cleanup.
Cleanup works best when you follow a clear order. Start with the accounts that matter most to a lender, then fix the details.
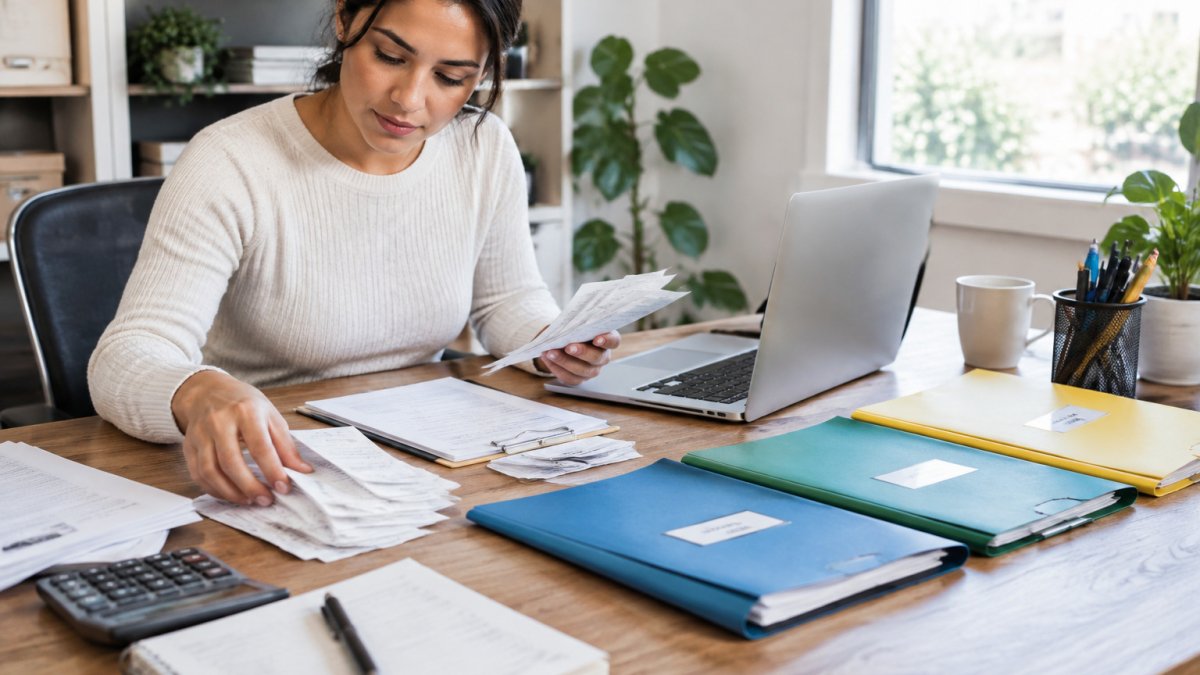
!A small business owner at a tidy desk sorting printed bank statements and receipts into labeled folders beside a laptop
Reconciliation means matching your books to your bank and card statements. Work through one account at a time, starting with the most recent month:
Reconciling even three to six months can make a big difference. Once those months balance, lenders can trust the rest of your records more easily.
Errors are normal. The goal is to find them and fix them in a consistent way. Start with the largest categories and the largest amounts. Then review uncategorized transactions in batches, using your bank's descriptions and receipts as guides.
When you correct an entry, keep a short note of why you changed it. This record helps you explain changes if a lender asks.
Cleanup time depends on how much work your books need. A business with a few months of gaps may need a few weeks. A business that has not reconciled in a year may need much longer. The number of accounts, the volume of transactions, and how far back the records go generally affect cleanup time.
Several factors change both the timeline and the professional fees:
Bookkeeping fees vary, and some providers quote a cleanup project after reviewing the file. Ask for a written scope that states which months and accounts are included, and confirm whether the fee covers reconciliation only or also categorization and financial statement preparation.
If you need funding soon, prioritize the work a lender will actually review. Use this plan:
If you have less than a month, focus only on the most recent three months of bank statements and a revenue summary. Some lenders may accept that combination while you finish the rest of the cleanup. Confirm requirements with each lender before you apply.
Watch out: Do not backdate or overwrite entries to make the numbers look cleaner. Lenders and accountants can detect altered records, and unexplained changes can end an application.
The U.S. Small Business Administration offers loan programs for many small businesses, and its microloan program provides loans of up to $50,000. U.S. Small Business Administration microloan program details SBA programs usually require detailed documentation, including tax returns, financial statements, and sometimes a business plan, so messy books can slow an application (Small Loan Submission Checklist & Cover Sheet).
Use this checklist before you apply:
If an SBA loan is not a good fit, other financing paths may work.
| Financing option | Documentation often required | Trade-offs to weigh |
|---|---|---|
| Bank term loan | Two to three years of tax returns, financial statements, debt schedule | Lowest rates for strong files; slowest approval and strictest bookkeeping standards |
| SBA-backed loan | Tax returns, financial statements, business plan, personal financial statement | Lower down payments and longer terms, but heavy paperwork and a longer timeline |
| Online term loan | Six to twelve months of bank statements, sometimes a profit and loss statement | Faster decisions, but higher rates and fees than bank loans |
| Business line of credit | Bank statements, revenue summary, sometimes tax returns | Flexible draws for ongoing needs, but variable rates and annual fees |
| Invoice financing | Outstanding invoices, customer list, accounts receivable aging | Advances cash against unpaid invoices, but fees reduce proceeds and customers may be contacted |
| Merchant cash advance | Recent card or sales processing statements | Fast funding repaid from future sales, but effective cost can be very high |
Some lenders focus more on bank activity than on a polished general ledger. If you want to see how a working capital term loan fits your situation, DollarHub's term loan overview explains how the structure works. When you are ready to compare options side by side, our guide to comparing business term loan rates and terms walks through the key numbers to check.
DollarHub's AI guidance system can help you narrow the choice based on your sales volume and cash flow, and total costs are presented upfront.
Watch out: Merchant cash advances can carry a high effective cost, so compare the total repayment amount, not just the daily or weekly payment.
Messy books are a solvable problem, and many owners get approved after cleaning up their records. If you are not sure where your books stand, DollarHub can help you decide what to fix first and which funding option may fit. DollarHub's streamlined three-step application process targets funding decisions within 24-48 hours, and total costs are shown before you accept anything.
Often yes, but messy books slow the process and can lower your chances with some lenders. Lenders look for records that show revenue, expenses and cash flow clearly. If your books are behind, reconcile your bank and credit card accounts first, categorize uncategorized transactions, and gather recent bank statements and tax returns. Some lenders weigh recent bank activity more heavily when formal bookkeeping is incomplete. Apply to lenders whose requirements match what you can document now, and be ready to explain any discrepancies.
Lenders commonly request recent business bank statements, personal and business tax returns, a profit and loss statement, a balance sheet, and sometimes a cash flow statement. Requirements vary by lender and loan type. SBA-backed loans typically require more documentation than merchant cash advances. Ask the lender for its exact document list before you start so you can gather everything in one pass.
The timeline depends on how many months are behind and how many transactions need review. A business with a few months of unreconciled activity may finish in a few weeks, while a multi-year backlog can take considerably longer. Start with the most recent months, since lenders focus heavily on current performance, and work backward. Bringing in a bookkeeper can shorten the timeline, though it adds cost.
Yes. A bookkeeper can reconcile accounts, categorize transactions and produce a profit and loss statement and balance sheet that lenders can review. An accountant can also review the statements for accuracy. Ask whether the statements will be prepared on an accrual or cash basis and whether the lender accepts that format.
 Add dollarhub.com as a preferred source on Google →
Get business loan approval in 24 hours by choosing lenders that decide fast and preparing the documents they ask for first.
Seasonal business cash flow gets tight in slow months. Learn how to build a 12-month forecast, set cash reserves and plan financing before the gap hits.
Learn how to get a business loan with bad credit, from checking lender requirements to preparing documents and comparing alternatives before you apply.